Practice areas · 02

Assurance and accounting

Controls reviews and accounting advice where the evidence, the review steps and the person responsible for each conclusion stay on the file.

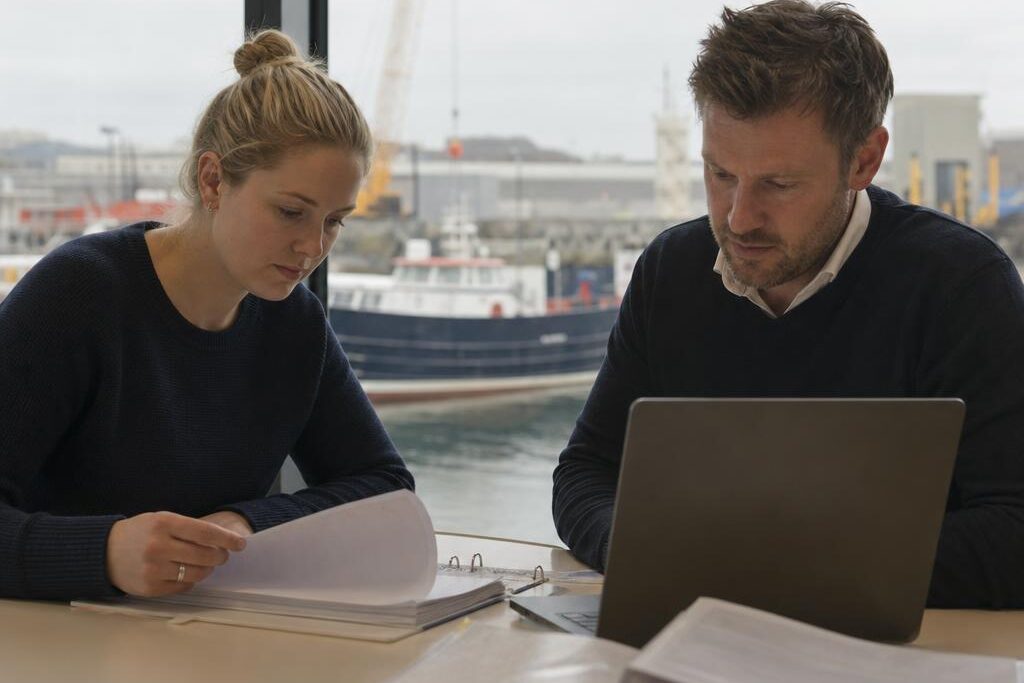
Two reviewers working through binders at a window overlooking a working harbour with a moored vessel
Fig. 1 · Working through the evidence binders, harbourside

§ 1

What the practice does

  • Controls reviews: a process inventory, evidence that controls operate, and a testing summary.
  • Reporting support and accounting advice, scoped in writing before work begins.
  • A prioritised improvement memo, reviewed by the engagement partner before release.

§ 2

From the file

Case note: a nine-week controls review

Client
Orrin Marine
Matter
2057
Duration
9 weeks
Reviewer
Harriet Larkspur

Orrin Marine commissioned a controls review: an agreed process inventory, a controls testing summary and a prioritised improvement memo. It is not an audit opinion, and the statement of work says so in its first section.

Week one confirms the scope. The team then collects evidence that each control actually operates. When an interview is missed, it is recorded as a dependency with an owner and a follow-up date. Nobody fills the gap with an assumption.

Everything the team gathers stays in the Orrin Marine matter. No other client's schedules or conclusions are used as evidence, and the partner review comes before the final memo.
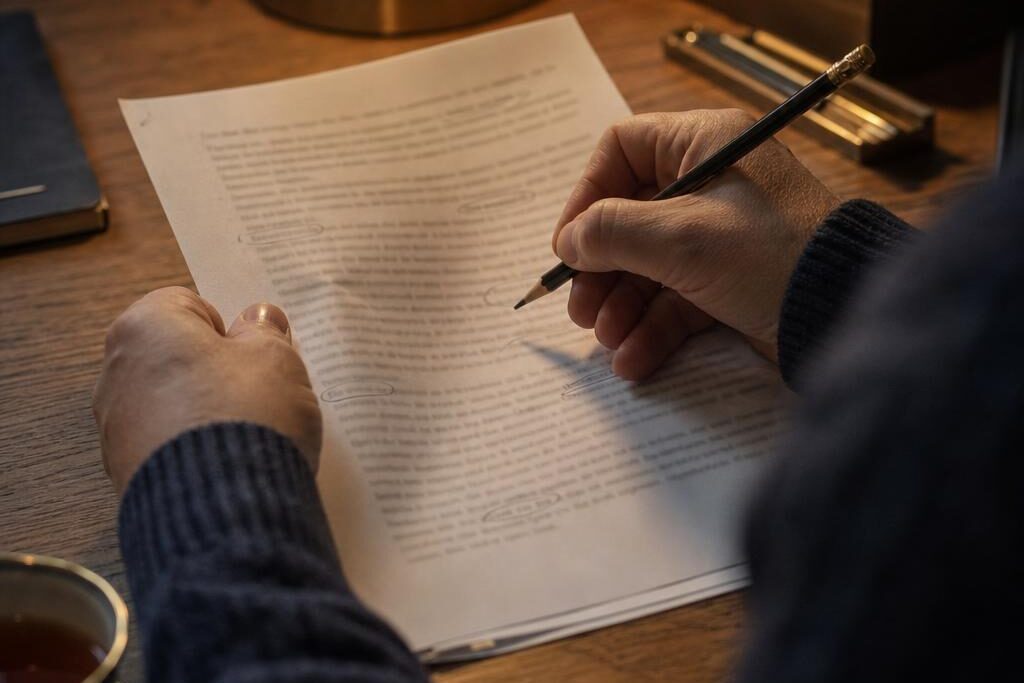
Hands marking a typed memo with a pencil under a brass desk lamp
Fig. 2 · A testing summary marked up before partner review

§ 3

How the work is reviewed

Harriet reviews the testing scope and the final release. Testing beyond the agreed inventory needs a written scope change before the team commits.