Practice areas · 01

Tax advisory

A written memo that names the rule in force, the section it relies on, and the guidance it replaces.

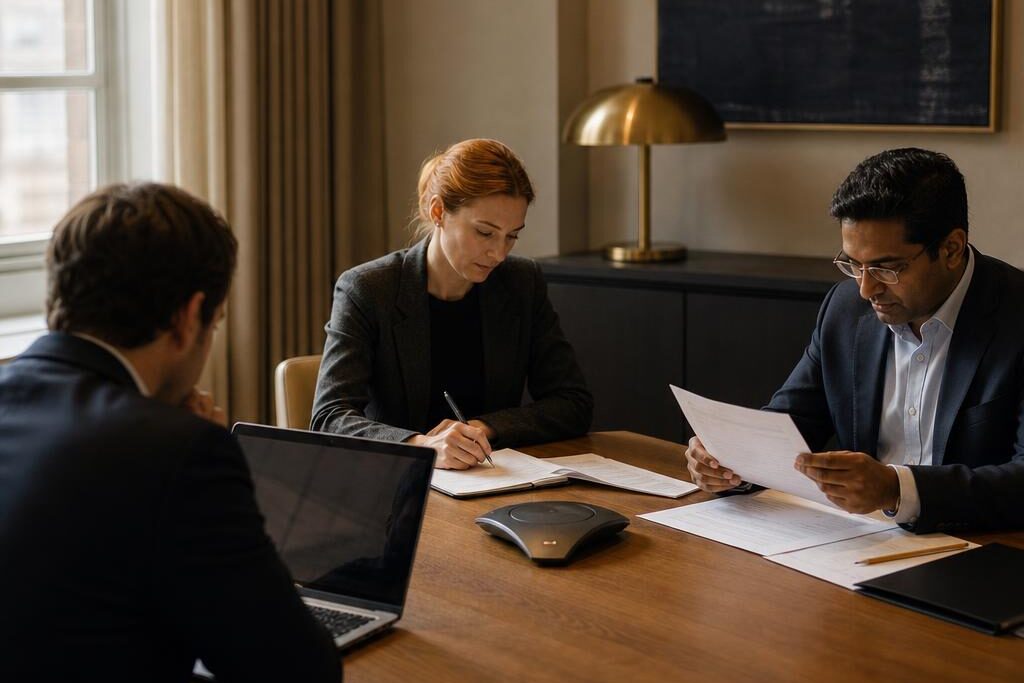
Three colleagues around a meeting table with papers and a laptop, preparing for a client call
Fig. 1 · Preparing for a board call, 14 Calder Row

§ 1

What the practice does

  • Research on a client question, recorded with the source, the section and the effective period.
  • Planning advice for a defined period, under a signed engagement letter.
  • A written advisory memo, reviewed by a tax partner before it leaves the matter team.

§ 2

From the file

Case note: a figure checked before a board call

Client
Halden Foods
Matter
2041
Terms
fixed fee, 25% deposit, net 21
Team
Rohan Mehta, Elena Marsh

Halden Foods asked for the immediate expensing limit for qualifying equipment ahead of its board preparation call. Last year's working memo gave 1,160,000, taken from Tax Advisory Memo TA-25-02.

Elena did not reuse the number. She checked the source and found that Tax Advisory Memo TA-26-04, issued in March, supersedes it for tax years beginning in 2026. Section 2 gives 1,250,000. The draft now carries the replacement figure with its citation, and names TA-25-02 as superseded rather than pretending it never existed.

Her research note is shared with the Halden Foods matter team only. Before release, Rohan still has to confirm the equipment qualification and the period. Until he does, the memo stays inside the team.
An open ring binder of schedules on a library table beside a fountain pen, reading glasses and a cup of tea
Fig. 2 · Schedules, the memo in force and a cold cup of tea

The memo figures on this page belong to a fictional firm. They are not real tax guidance.

§ 3

How the work is reviewed

Rohan reviews every qualification analysis. The engagement letter covers a written memo and one board preparation call; extra equipment modelling is a written change request with fee, timing and reviewer agreed first.